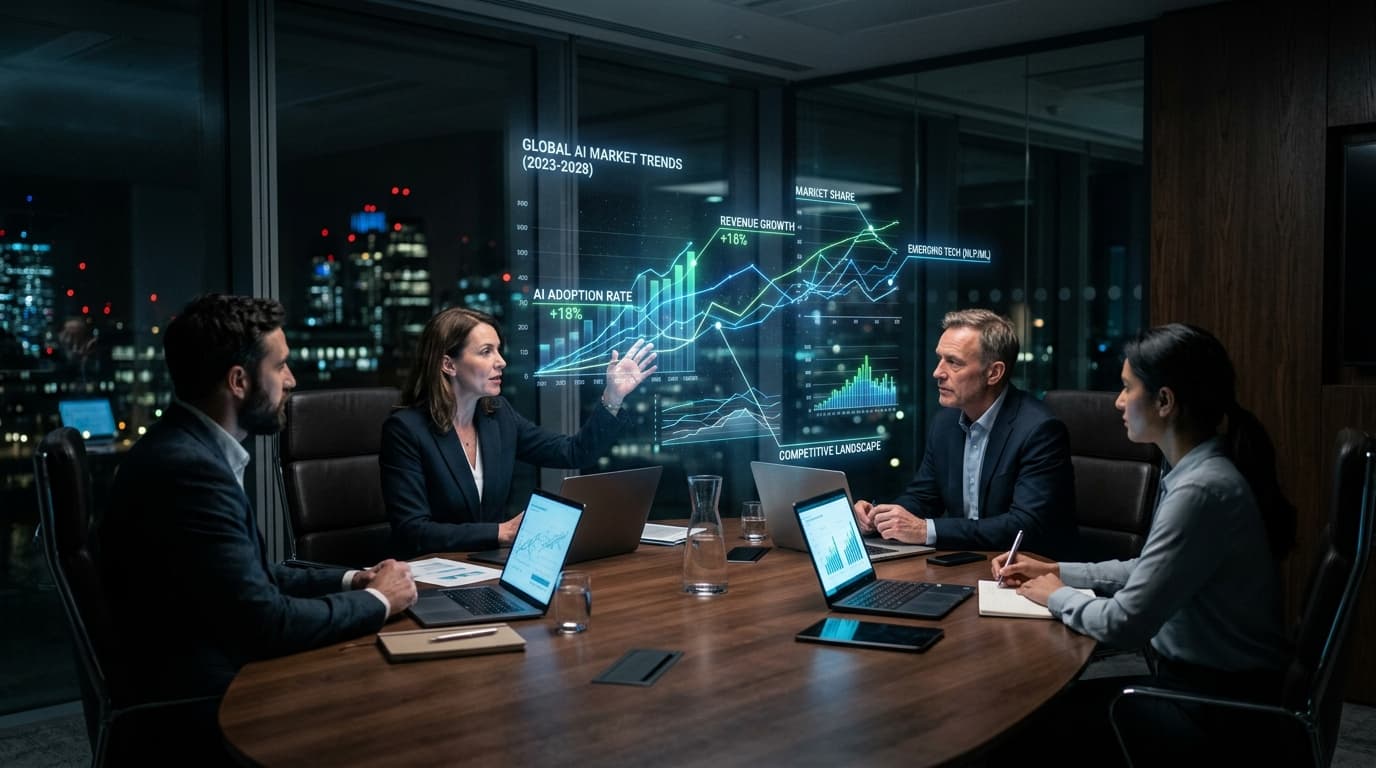
In a recent quarter, Morgan Stanley's wealth management division reported strong results, generating substantial revenue with record asset management fees. Simultaneously, across the financial landscape, Citadel's flagship Wellington fund delivered robust performance, finishing a recent year with significant returns. This juxtaposition prompts a critical examination: how does a traditional wealth manager's established assumptions about client engagement and revenue streams contrast with a hedge fund's dynamic, data-driven approach to market shifts, particularly regarding underlying governance and adaptive responsiveness?
This involves more than a tale of two financial giants; it is a study in strategic operating models. Morgan Stanley, a venerable institution, expanded its wealth management reach significantly through the 2020 E*TRADE acquisition. This move cemented its focus on serving a broad spectrum of retail investors. Conversely, Citadel, a formidable hedge fund, has long honed its edge through sophisticated quantitative models and data-driven prowess across diverse asset classes. The divergence in their approaches exposes a fundamental challenge faced by many large organizations today: the critical difference between operating on unchanging assumptions versus continuously adapting to real-time market signals. The core thesis here is that Morgan Stanley’s deep-seated beliefs about retail investor loyalty and revenue generation are silently losing their relevance, while Citadel’s responsive systems allow for constant recalibration—revealing a significant delay in organizational adaptation that can diminish overall profitability.
Unchanging Revenue Models
Morgan Stanley’s strategy post-E*TRADE acquisition underscored a commitment to expanding its retail investor base. The firm anticipated sustained inflows from this segment, building on an existing advisor-driven structure. This strategy often relies on predictable, percentage-based advisory fees, commonly based on a percentage of assets under management (AUM). Such a model, while providing stable income streams in buoyant markets, carries inherent rigidities. The governance framework supporting this structure tends to be cyclical, often involving annual client reviews and periodic portfolio rebalancing. This approach prioritizes long-term relationships and broad market exposure, assuming a relatively consistent economic environment and client behavior. The organizational design and compensation structures within such a framework frequently reward asset gathering and client retention, incentivizing stability over rapid adjustment.
Consider the operational implications: a fee structure tied to AUM rewards the accumulation of assets over dynamic adjustments to market volatility or evolving investor preferences. Sales commission models and executive bonus structures may be heavily weighted towards expanding the client base and increasing managed assets, potentially overlooking the underlying resilience of these revenue streams against external shocks. When these assumptions hold, the model appears robust. However, when market conditions shift, the enterprise finds itself steering a large vessel with a slow-to-respond rudder. This creates a significant drag on strategic execution, a concept explored further in our analysis of unmasking strategic assumption drag. The internal incentives, designed for growth under specific market conditions, can inadvertently disincentivize the agility needed when those conditions change.
In stark contrast, Citadel’s operational framework thrives on dynamic performance-based fee models. These fees are directly tied to the firm's trading profits, often structured to capture a share of positive returns. This incentivizes continuous, real-time risk assessment and data-driven adaptation to exploit fleeting market opportunities. Citadel's governance model is inherently driven by live data feeds, using sophisticated systems to monitor and respond to market signals within milliseconds. Their systems are built for constant recalibration, stress-testing assumptions against immediate market feedback. This necessitates a decentralized organizational design where quantitative researchers and engineers are empowered to deploy advanced computational tools with speed and precision, supported by robust, centralized risk oversight. Compensation at Citadel is intrinsically linked to performance, directly aligning individual and team outcomes with the firm’s overall profitability, fostered by a culture of immediate feedback and adjustment. The underlying belief is that markets are in a constant state of flux, demanding an equally fluid strategic posture. This philosophical divide influences everything from daily trading decisions to long-term talent acquisition and technology investment.
| Governance Model | Fee Structure | Assumption Monitoring | Earnings Robustness |
|---|---|---|---|
| Morgan Stanley Wealth Mgmt | Traditional advisory | Annual client reviews | Exposed to market shifts |
| Citadel Hedge Funds | Performance-based | Real-time systems | Strong (demonstrated high returns) |
| Mastercard Payment Net | Transaction-based | Real-time fraud detection | Growing (demonstrated consistent growth) |
The Delay in Resource Deployment
The divergent governance models naturally lead to distinct approaches to resource deployment. Morgan Stanley, with its extensive retail network, has historically committed to multi-year initiatives involving physical infrastructure. For instance, in 2023, the firm continued its strategic emphasis on its consumer deposit franchise, indicating sustained focus on a model that often involves branch presence or an expanding advisor network. While details on specific new branch expansion plans in 2023 are qualitative in nature within investor presentations, the overarching strategy underlines substantial allocations to physical presence and a broad advisor footprint. Such undertakings represent significant, long-cycle commitments, where the return on deployed resources may take years to materialize. The decision-making process for such large-scale initiatives is typically hierarchical and involves extended planning cycles, reflecting the longer time horizons of traditional financial institutions. This approach, while fostering stability and trust, inherently limits the agility to redirect resources swiftly in response to unforeseen market shifts or competitive pressures.
By contrast, Citadel operates with a far more liquid and data-driven resource reallocation mechanism. Its operating procedures allow for immediate adjustments to its trading positions and systematic strategies. The firm actively invests in artificial intelligence to enhance its trading capabilities, with a reported shift towards AI-powered arbitrage. This involves more than incremental improvements; it entails a fundamental redesign of its operational core. For example, reports highlight Citadel's agentic AI's ability to replicate advanced finance research in a matter of hours, a task that traditionally takes weeks. This capability enables near real-time validation and adaptation of trading strategies, ensuring that resources are continuously directed towards the most promising opportunities identified by its sophisticated systems. Such a framework necessitates minimal organizational friction in reallocating computational power, data scientists, and trading capital. The incentives are geared towards identifying and exploiting new data sources and developing novel systems, with success measured by immediate, tangible returns. This adaptability avoids the financial cost of prolonged sub-optimal strategies, a concept critical for any organization seeking to manage its Strategic Drag.
When Core Beliefs Lose Relevance
Morgan Stanley’s 2020 acquisition of E*TRADE was predicated on fundamental beliefs about the sustained growth and loyalty of retail investors. The expectation was that a surge in retail engagement, evident during the early phases of the pandemic, would continue, driving consistent asset inflows. Indeed, retail investor sentiment hit record highs in early 2023, with substantial daily net inflows during that period. However, the assumption that this trend would translate into perpetually robust fee structures and unwavering loyalty faced challenges. By 2023, market conditions were marked by rising inflation and climbing bond yields, which influenced investor behavior. These subtle shifts in investor sentiment and behavior, coupled with broader market volatility, silently diminished the underlying value of a strategy built on prior assumptions, effectively expiring key beliefs.
This is where a significant governance challenge emerges. Organizational structures and reporting lines within large, traditional financial institutions may not be designed to detect these subtle erosions of core assumptions in real-time. Key performance indicators might continue to show aggregated growth, masking a gradual deterioration in profitability or increased client churn in specific segments. The incentive structures, which reward the accumulation of assets, may not adequately penalize the slow adaptation to a changing competitive landscape where investors are increasingly seeking diverse options. This can lead to a considerable delay in strategic reassessment, where significant changes are only acknowledged when they appear starkly in quarterly reports, rather than being flagged as they develop.
Citadel’s approach provides a powerful counterpoint. Its operational model incorporates live stress-testing and continuous monitoring of underlying assumptions. The firm's culture, driven by quantitative analysis and immediate feedback, means that any deviation from expected market behavior or performance triggers an immediate systematic or human review. For example, Citadel’s response to the 2022 period of significant market turbulence for quantitative strategies would have involved immediate recalibration of its systems and portfolios. The firm's continuous recruitment of AI researchers and its focus on developing agentic AI that can validate research rapidly underscore a commitment to maintaining a dynamically adaptable assumption set. This ongoing, rigorous challenge of underlying beliefs is deeply embedded in the firm’s operational ethos and forms the cornerstone of its risk management. In effect, Citadel treats its strategic assumptions not as immutable truths, but as hypotheses that require constant, real-time validation, a fundamental aspect of adaptive business the cost of assumptions.
Adapting to Real-Time Governance
The contrasting journeys of Morgan Stanley and Citadel reveal a profound lesson for executive leadership: the enduring criticality of dynamic governance. The traditional paradigm of strategy development, often characterized by multi-year plans and periodic reviews, struggles to contend with markets that adapt with rapid velocity. Morgan Stanley’s strategic pursuit of a larger retail wealth management footprint, while sound in its initial premise, becomes vulnerable when its foundational beliefs about client behavior and predictable revenue models are not continuously verified. The human element, with its inherent biases and slower processing, faces an overwhelming challenge against an environment where market signals fluctuate by the second.
Consider the operational risk: an executive team, relying on reports and dashboards updated quarterly or even monthly, might inadvertently perpetuate a strategy that is silently losing its effectiveness. They may look at overall wealth management asset growth and miss the subtle shifts in client engagement, the rising cost of retaining clients, or the changing competitive dynamics for fee structures. The true realization hits like a sudden shock: "We are managing this exact strategic risk in fixed slide decks and disconnected spreadsheets right now—if one assumption shifts next month, we won't see the ripple effect until it hits our P&L."
This is precisely where Strategy OS provides a crucial advantage. Just as Mastercard's payment network employs real-time fraud detection—a system that constantly monitors transactional data for anomalies and instantly flags deviations—enterprise governance demands similar responsiveness. Strategy OS offers the capability to continuously monitor strategic assumptions against real-time market data, competitive actions, and operational performance. It moves beyond quarterly reports to provide a granular, always-on view of how underlying strategic beliefs are performing against reality. This is not about automating decision-making entirely, but about augmenting executive judgment with a system that can flag when critical assumptions are becoming irrelevant, allowing for proactive adjustment rather than reactive damage control. It is about empowering leaders to monitor assumptions like a hedge fund, and govern like a resilient, adaptive enterprise. To understand how such continuous calibration can transform your organization's responsiveness, delve into our Ultimate Strategic Planning Guide.
Begin to truly understand and quantify the impact of unverified assumptions on your enterprise. Start your 7-day Pro reverse trial with Strategy OS →
Explore the Financial Services Capital Allocation in Full 3D
Decision Latency Cost, Yield Optimization & Automated Regulatory Shield. Test real-time scenario adjustments and observe strategic drag shifts live without setting up an account.
Quantify Your Organization's Strategic Drag
Static annual roadmaps and decision latency cost enterprise teams an estimated 15% in lost execution velocity. Run our 60-second diagnostic to calculate your dollar drag.
Start Playing with Strategy OS
Transform your static plans into dynamic knowledge with our AI-powered strategic platform.
Start Free Trial